Acorns Early: Kids Money App
Acorns
- 4.5
- 533.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
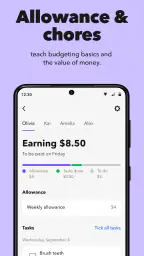
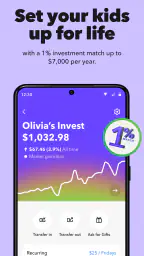
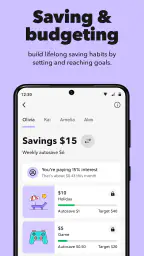
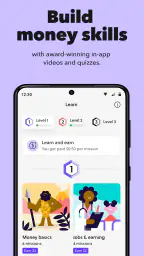
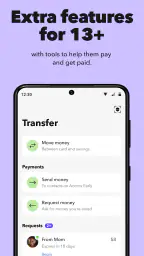
Acorns Early: Kids Money App Pros and Cons
Pros
- Teaches saving habits through simple, child-friendly money lessons.
- Parents can set goals and track progress from their own account.
- Automated investing can help families build long-term savings gradually.
- Designed for supervised use, keeping parents involved in money decisions.
- Useful gift option for relatives who want to contribute to a child’s future.
Cons
- Requires an eligible Acorns subscription, adding an ongoing cost.
- Availability and features may vary by country or account type.
- Young children may need help understanding investing risks and returns.
- Some features depend on a parent’s linked bank or Acorns account.
- Investment values can fall, so savings are not guaranteed to grow.
 Analysis by All-app
I approached Acorns Early as a parent-facing finance app rather than as another colorful money game. Its purpose is to help families build better financial habits for children and teenagers through an investing plan, but the more interesting question is how comfortably different people can actually use it. A useful money tool needs to be understandable when a child is learning a new idea, manageable for a busy parent, and clear enough that important choices do not get lost behind polished screens.
My overall impression is positive but measured. The app feels most suitable for families who want to introduce long-term saving and investing gradually, with an adult guiding the process. It is less convincing as a complete financial education system on its own, and it is not the obvious choice for someone who wants detailed trading controls, advanced portfolio analysis, or a fully independent experience for a young user. That distinction matters: the app’s strength is making an intimidating subject feel approachable, not replacing every other tool a family may need.
How Acorns Early feels to use across different needs
I look at Acorns Early through the different demands a family brings to a finance app: a parent may want a manageable routine, while a child needs explanations that feel clear rather than intimidating. That makes the experience less about one perfect screen and more about whether the investing plan can support a useful conversation. From there, it is worth considering which everyday family situation makes that approach most practical.
Readable screens and a navigation style that favors beginners
The first thing I noticed was the app’s beginner-friendly tone. Finance apps often assume that users already understand terms such as diversification, risk, contributions, and market movement. Acorns Early is built around a much simpler starting point: helping a child or teenager develop financial wellness through an investing plan. That makes the product easier to discuss at home because the parent can begin with the goal rather than immediately explaining a complicated dashboard.
For a new user, that simplicity is useful. A parent who is already comfortable with investing can move quickly, while someone who finds financial language intimidating has a gentler entry point. I also think this approach benefits teenagers who may understand spending but have never connected everyday choices with longer-term goals. The app’s focus gives conversations a practical direction instead of turning them into an abstract lesson about markets.
There is a trade-off, though. A simplified presentation can hide important nuance if the user assumes that investing is automatically straightforward. I would use the app as a starting point for conversations, not as a substitute for explaining that investments can rise and fall, that time horizons matter, and that a child’s needs are different from an adult’s. The clearer the parent is about those limits, the more useful the app becomes.
Navigation also needs to work for adults who are tired, distracted, or checking something quickly between other tasks. In that situation, a short path to the relevant information is more valuable than a screen packed with charts. Acorns Early appears designed for that kind of approachable interaction. Still, parents should take their time when setting up or reviewing an investing plan. A friendly interface should not encourage anyone to rush through financial decisions.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Readability is not only about large text or clean spacing. It is also about whether the meaning of a choice is obvious. I would pay close attention to labels, explanations, and confirmation screens, especially when using the app with a child. If a young user can repeat the purpose of a contribution or explain what the plan is trying to achieve, that is a better test than whether the screen simply looks uncluttered.
Supporting different learning styles without turning money into a lecture
Children and teenagers do not all learn about money in the same way. Some respond to a visible goal, some prefer a conversation, and others need to see a routine repeated before it makes sense. The app’s investing-plan focus can support the first two approaches, but the family still has to supply the context. I would pair a screen review with a simple real-life example, such as connecting a regular saving habit to a future purchase or a longer-term personal goal.
One practical workflow is to review the plan at a calm time rather than opening it only when a contribution is being made. Ask the child what they think the plan is for, what they expect over a long period, and which parts they do not understand. This turns the app into a prompt for financial literacy instead of a silent background service. It also reveals whether the wording is genuinely clear to that particular child.
For teenagers, I would avoid presenting the app as a shortcut to wealth. The strongest lesson is consistency and patience. A parent can use the plan to explain why a long-term approach may look uneventful from week to week, and why short-term changes should not automatically trigger a reaction. That is a more responsible use of the product than treating the balance like a game score.
Motor and sensory considerations in everyday use
Finance apps are often used with one hand, on a small phone, in a moving car while stopped, in a noisy room, or late at night. Those conditions create access challenges even when a person has no disability. I found the app’s beginner-oriented purpose helpful because it does not require the user to interpret a professional trading terminal. Fewer competing ideas on screen can reduce cognitive load for people who become overwhelmed by dense financial interfaces.
That said, I would not assume that a clean design solves every motor or sensory issue. A person with limited dexterity may need more time for taps, scrolling, or confirmation steps. Someone with low vision may depend on the phone’s own text enlargement, contrast, or screen-reading tools, and the real experience can vary by device and operating-system settings. A user with attention difficulties may benefit from reviewing one task at a time rather than exploring every available option in a single session.
Parents can make the experience more comfortable by setting up the app in a quiet environment, increasing device text size when necessary, and avoiding rushed decisions on a small screen. If a child uses assistive technology, I would test the complete flow together before relying on it for an important financial action. The key question is not whether the app looks accessible in a screenshot, but whether the child can understand where they are, what will happen next, and how to recover from a mistaken tap.
Sensory comfort also includes emotional tone. Money can be stressful, particularly for families dealing with tight budgets or previous financial mistakes. A calm, non-judgmental conversation around the app is important. I would not use it to pressure a child into comparing their progress with friends or relatives. Its value is greater when it supports confidence and understanding rather than competition.
Situational access for parents, children, and teenagers
The app is free to install, carries an Everyone age rating, and comes from Acorns. It was released on November 8, 2024, and the current version is 9.6.1, with support beginning at Android 7.0. Those details make it approachable for families using older Android hardware, although the quality of the experience can still depend on the individual phone, display, and system settings.
In a realistic family scenario, a parent might open the app after a teenager receives regular pocket money. Instead of handing over a complicated investing account, the parent can use the plan as a structured way to discuss what portion of money is for immediate needs and what portion is intended for the future. The teenager does not need to understand every financial concept on the first day. A short review every few weeks can gradually build familiarity.
Another useful situation is a family with limited time. A parent may want a simple routine that can be checked without sitting down for a full budgeting session. Acorns Early is better suited to that light-touch rhythm than to detailed household accounting. However, that convenience can become a weakness if the family needs a complete view of spending, bills, debt, and cash flow. In that case, a dedicated budgeting app or a spreadsheet may be the better companion.
It can also help when a child is curious but not ready for independent financial management. The adult remains central to the process, while the child gets an understandable subject to ask about. I would keep the first sessions collaborative: explain the purpose, invite questions, and make sure the child knows that investing is not the same as having instantly available spending money.
Families should also consider their internet and device circumstances. A person who shares a phone, has limited data, or can only use the app in short bursts may find setup and review less convenient. Someone who needs offline access to key information may prefer a paper-based learning plan alongside the app. Digital access is situational, and a finance product should fit the household’s actual routine rather than forcing the household to reorganize around it.
Where it differs from ordinary money apps
The usual alternatives fall into several groups. A basic allowance tracker focuses on chores, spending, or saving goals. A budgeting app usually concentrates on categories and cash flow. A brokerage app is aimed at adults who want more control and more market detail. Acorns Early occupies a middle ground: it is more future-focused than a simple allowance tool, but less demanding than a full investment platform.
That middle position is its main advantage. Parents who want to introduce investing without placing a professional-looking terminal in front of a child may appreciate the softer learning curve. The app also gives the conversation a concrete anchor. Rather than saying “you should think about the future,” a parent can talk about the plan and ask whether the child understands its purpose.
The compromise is control and depth. If you want to compare securities, build a highly customized portfolio, examine detailed performance information, or manage a broader financial picture, a traditional investment or budgeting service will likely serve you better. I would not choose Acorns Early for a financially experienced adult who simply wants a powerful portfolio dashboard.
It is also different from a purely educational game. A game can teach concepts through fictional rewards and immediate feedback, while this app is connected to a real financial habit. That makes the lesson more meaningful, but it also means the adult must explain consequences carefully. The child should understand that a real plan deserves patience and attention, not impulsive experimentation.
Remaining barriers and the friction parents should expect
The biggest barrier is not necessarily navigation; it is the subject itself. Investing can sound simple when reduced to a goal and a plan, but families still need to discuss uncertainty, time, and responsibility. A polished experience can make those ideas feel less visible. I would treat every simplified explanation as an opening for a follow-up question, not as the whole lesson.
Another limitation is the dependence on an involved adult. The app’s audience includes kids and teens, but that does not mean every young user will get the same value from it independently. A child who needs step-by-step support may benefit greatly from shared use, while a teenager seeking autonomy may find the adult-led structure restrictive. Before choosing it, parents should decide how much guidance they are realistically prepared to provide.
There is also a risk of mismatch between the app and a family’s financial priorities. If the household is trying to control everyday spending, build an emergency cushion, or understand debt, investing for a child may not be the first task to address. In that situation, a budgeting conversation should come before an investing routine. The app can be useful later, but it should not distract from more urgent financial needs.
Accessibility remains something I would test personally rather than assume. Device settings can help with text size, contrast, touch response, and screen reading, but the complete experience may still be difficult for some users. If a child cannot comfortably read an explanation, identify a selected option, or confirm an action, the family should slow down and consider another method. A financial habit is not successful if the person it is meant to serve cannot participate meaningfully.
Finally, the app may feel too limited for families who want one place for every money task. I would not expect it to replace a household budget, a spending tracker, a bank account, and an adult investment platform. Its role is narrower and clearer: provide a child- or teen-oriented route into long-term financial thinking. Keeping that role in mind prevents disappointment.
My inclusive verdict on Acorns Early
Acorns Early has a sensible place in a family’s financial toolkit. With an average rating of 4.5 from around 3.1 thousand ratings and more than 100 thousand installs, it has attracted a meaningful audience, while its free availability lowers the barrier to trying it. Those numbers do not prove that it will suit every household, but they do suggest that the approachable concept resonates with many users.
I would recommend it to parents who want a gentle, structured way to introduce investing to a child or teenager and who are willing to stay involved. It is particularly promising for families that find conventional investment apps too technical and allowance trackers too focused on short-term spending. The best results will come from using it as part of regular conversations, not from handing it to a child and expecting the interface to teach everything automatically.
I would steer different users elsewhere when they need advanced investment control, detailed budgeting, offline materials, or a completely independent experience for a young person. I would also wait if the family’s immediate financial priorities are basic cash management rather than long-term investing. Those are not failures of the app; they are signs that its focused purpose may not match the current situation.
My final judgment is that the app’s strongest accessibility feature is its attempt to reduce intimidation. It gives families a more approachable starting point and can make an unfamiliar topic easier to discuss. Its remaining challenge is ensuring that simplicity does not hide complexity or leave users who need more support behind. Used patiently, with device settings adjusted to the child and the adult explaining the important ideas, it can be a useful bridge between pocket money and long-term financial awareness. For me, the right reason to choose it is not convenience alone, but the chance to make financial learning a shared, understandable routine.
Frequently Asked Questions
What is Acorns Early: Kids Money App, and who is it designed for?
Acorns Early: Kids Money App is a family-focused financial education and money management tool designed to help parents introduce children to saving, spending, earning, and responsible money habits. Parents generally control the account and settings, while children can use age-appropriate features to learn about money through practical activities and guided experiences. It is best suited to families who want to discuss finances together rather than give children completely independent control.
Does Acorns Early require a parent or guardian account?
Yes, parental involvement is an important part of the experience. A parent or legal guardian typically needs to create and manage the family account, review available features, and decide how children can access money-related tools. Before downloading, parents should check the current eligibility rules, supported locations, identity-verification requirements, and any subscription or account conditions, since these details may vary by region and can change with app updates.
Can children make purchases or use a card through Acorns Early?
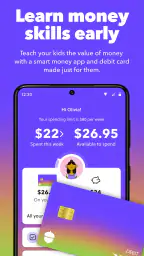
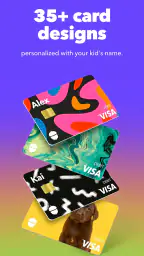
Depending on the child’s age, the parent’s plan, and the features available in the user’s region, Acorns Early may provide tools that allow children to practice spending under parental supervision. Parents should review transaction controls, spending limits, notifications, merchant restrictions, and card-related fees before enabling these options. The app is intended to support guided learning, so it should complement regular conversations about safe and responsible spending.
Is Acorns Early free to download and use?
The app may be free to download, but some services can depend on a paid Acorns membership, an eligible family plan, or other account conditions. Potential costs may include recurring subscription charges, optional financial products, card fees, or transaction-related expenses. Because pricing and availability can change, parents should read the latest information in the official app listing and Acorns’ terms before creating an account or activating any paid feature.
Is Acorns Early safe for children, and what should parents consider about privacy?
Acorns Early is built around parental oversight, but parents should still examine the app’s privacy policy, permissions, data practices, and account-security options before allowing a child to use it. Avoid sharing login details, enable available security protections, and explain why personal information should not be disclosed to other users. Parents should also supervise use regularly and confirm that the app’s age requirements and features are appropriate for their child.